Storage
DDR5 Server DRAM Supply Gap Through 2027: The AI Server Memory Configuration Math
The server-memory shortage is not explained by counting AI accelerators alone. It is also a configuration problem: how many host systems are deployed, how much working memory each requires, which modules are qualified, and how quickly manufacturers can deliver the appropriate mix.
Kioxia’s 45x Profit Jump: NAND Price Surge and Enterprise SSD Demand
Kioxia’s latest profit surge illustrates what happens when higher semiconductor prices meet a manufacturing business with substantial operating leverage. Stronger demand improves revenue, while a large portion of the resulting gain can reach profit if production costs do not rise at the same pace.
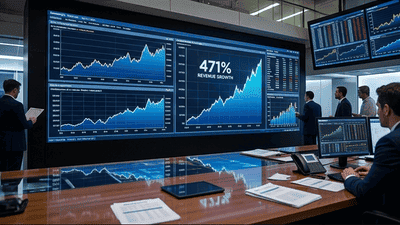
Samsung’s Memory Revenue Up 471%: Deconstructing the AI Storage Windfall
Samsung’s memory business is benefiting from a powerful combination: rising selling prices, stronger server demand, and a product mix increasingly shaped by AI infrastructure. The result is a revenue and profit expansion that is changing how investors evaluate an industry traditionally associated with steep cycles.

DRAM ETF Holdings Concentration: The Risk Behind the 73% Three-Stock Bet
A memory-focused ETF can provide convenient access to an industry whose products sit at the center of servers, AI infrastructure, smartphones, and enterprise storage. It can also create the impression of diversification without spreading the underlying economic risk very far.

Micron’s Completed PSMC Acquisition: The Taiwan DRAM Capacity Timeline
Micron’s completed Taiwan transaction gives the company an important asset in the race to expand memory production: an existing manufacturing site that can be adapted rather than built entirely from the ground up. But ownership is only the first milestone. The commercial value depends on retrofitting, equipment installation, process qualification, and the pace at which the facility produces accepted products.
Roundhill DRAM ETF’s $10B in 50 Days: The Fastest Thematic ETF Launch Ever
A narrowly focused memory fund became one of the most striking ETF launch stories of 2026. Investors were looking beyond processors and asking a different AI question: which companies supply the memory and storage that advanced computing systems cannot operate without?
SK Hynix Q2 DRAM ASP Up 30%: The AI Server Demand Curve
SK hynix’s second-quarter DRAM pricing tells a broader story than the success of high-bandwidth memory alone. The company reported that DRAM average selling prices rose approximately 30% sequentially in the April–June 2026 quarter, with management attributing the increase primarily to continued strength in conventional DRAM. DRAM bit shipments increased by a high-single-digit percentage.

Memory Inventory Days and Stock Price Lead-Lag: The 2026 Signal
Memory inventories and memory stocks rarely turn at the same moment. A share price can recover while reported inventory remains elevated, or weaken while manufacturers are still announcing strong sales. That apparent contradiction is often the most useful part of the signal: financial markets price expectations, while quarterly accounts describe conditions that have already developed.

NAND Layer Count Race: Kioxia’s 332-Layer BiCS10 Sample Delivery
Kioxia’s 332-layer BiCS10 NAND marks a meaningful step in the race to build denser, faster, and more power-efficient flash memory. Yet the most important word in the announcement is not “332.” It is “samples.” The technology has reached functional evaluation, while its commercial significance still depends on manufacturing execution and integration into qualified storage products.
Server DRAM vs. Mobile DRAM Price Divergence: Arbitrage Opportunity Analysis
The DRAM market is never perfectly synchronized. Even though server DRAM and mobile DRAM share common manufacturing roots, their price trajectories often diverge because each segment is driven by different demand cycles, product mixes, and strategic priorities. When that divergence becomes pronounced, it naturally raises the question: is there an arbitrage opportunity? Can manufacturers, module houses, or even investors exploit pricing gaps between server and mobile DRAM in a systematic way?