Storage

Application Advantages of ZNS SSDs in AI Training Scenarios
As AI training scales from single‑node experiments to massive distributed clusters, storage architecture has become a critical bottleneck. Traditional SSDs, while fast, are not always optimized for the write‑heavy, sequential, and log‑structured patterns that modern AI workloads generate. Zoned Namespace (ZNS) SSDs are designed to better match these patterns by reshaping how data is written and managed on flash. In AI training scenarios, the result can be higher throughput, lower write amplification, longer drive lifetimes, and more predictable performance.
Elasticity Model Between NAND Flash Bit Growth and ASP
The NAND flash industry lives at the intersection of relentless technological progress and equally relentless price pressure. Every year, process shrinks, 3D layer increases, and cell innovations expand the number of bits that can be produced per wafer. At the same time, average selling prices (ASP) tend to decline over the long run, making flash more affordable while challenging vendor margins. Understanding the elasticity between NAND flash bit growth and ASP—how changes in bit output relate to price movements—is essential for anyone forecasting the memory market or planning investments tied to storage costs.

Sensitivity Test of Module Makers’ Profit Margins to Wafer Prices
Memory module makers sit in a critical middle layer of the DRAM and NAND ecosystem. They do not fabricate wafers themselves, but they buy dies or components from upstream producers and convert them into finished modules—DIMMs, SSDs, embedded storage—that ship to OEMs, data centers, and distributors. Because of this position, their profit margins are highly exposed to movements in wafer and die prices. When upstream input costs rise or fall, module makers must decide how much of that change to absorb, how much to pass on, and how to adjust mix and strategy.
Memory Sector Beta vs. Individual Alpha: Passive Allocation or Active Stock Picking?
The global memory industry has moved from a quiet, cyclical corner of semiconductors to the center of attention thanks to AI, cloud computing, and high‑performance hardware. For investors, this shift raises a pressing question: is it enough to capture “sector beta” by owning broad exposure to memory, or does the complexity and dispersion within the industry justify an “individual alpha” approach focused on active stock picking? Put differently, should you treat memory like an index trade or like a hunting ground for idiosyncratic winners?
2026 Global DRAM Market Share Evolution: Samsung, SK Hynix, Micron
By 2026, the global DRAM industry remains highly concentrated around three familiar names: Samsung, SK Hynix, and Micron. Together, they still account for the vast majority of worldwide DRAM supply, but the balance of power among them is far from static. Changes in technology mix, product focus, regional demand, and strategic bets on emerging segments such as high‑bandwidth memory (HBM) and DDR5 have continued to reshape their respective positions.
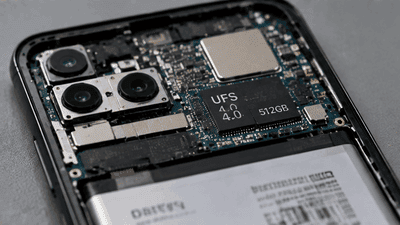
Embedded Storage (eMMC/UFS) Capacity Upgrade Trends in AI Smartphones
The rise of AI smartphones is quietly transforming the requirements for embedded storage, pushing both capacity and performance far beyond what was typical just a few years ago. In devices where on‑device AI models, multimodal data, and continuous sensing are becoming standard, traditional eMMC and UFS configurations are no longer sufficient. Instead, we are seeing a clear trend toward larger capacities and faster UFS generations, with eMMC gradually retreating to entry‑level and non‑AI use cases.
SLC NAND’s Irreplaceability and Price Resilience in Automotive and Industrial Sectors
In a memory market increasingly dominated by high‑density MLC, TLC, and QLC NAND for consumer and data‑center applications, single‑level cell (SLC) NAND looks, at first glance, like a relic of an earlier era. Its bit density is lower, its cost per bit is higher, and volume shipments are modest compared with mainstream flash. Yet in automotive and industrial sectors, SLC NAND remains stubbornly irreplaceable, and its pricing is remarkably resilient even as broader NAND markets swing through cycles of boom and bust.

The Disruptive Impact of CXL Memory Pooling on Enterprise Storage Architecture
Compute Express Link (CXL) is rapidly emerging as one of the most transformative technologies in enterprise infrastructure, and memory pooling is at the heart of its disruptive potential. By decoupling memory from individual servers and exposing it as a shared, dynamically allocable resource, CXL memory pooling challenges long‑standing assumptions about how enterprises design, deploy, and manage both compute and storage.
The Disruption of Global Memory Pricing by YMTC and CXMT Expansion
Global memory pricing has long been shaped by a relatively small group of dominant DRAM and NAND producers, whose investment cycles, technology transitions, and supply discipline set the tone for the entire industry. In recent years, however, China-based memory makers—most notably YMTC in NAND and CXMT in DRAM—have begun to expand capacity and capabilities in ways that challenge this traditional equilibrium. Their rise introduces new sources of bit supply, new technology roadmaps, and new strategic behaviors, all of which contribute to the disruption of global memory pricing.

Accelerated Localization of Flash Controllers: Breakthroughs by Yeestor and Maxio
In recent years, the global flash storage ecosystem has undergone a notable shift: controller technology, once dominated by a handful of international players, is rapidly localizing in key regional markets. Within this context, Yeestor and Maxio have emerged as emblematic examples of how local firms can achieve substantial breakthroughs in flash controller design, validation, and commercialization. Their progress reflects both technical maturation and a broader strategic push toward supply chain independence and differentiated, region‑specific solutions.